Theft, Value and the Garage Door: Protecting an MV Agusta in 2026
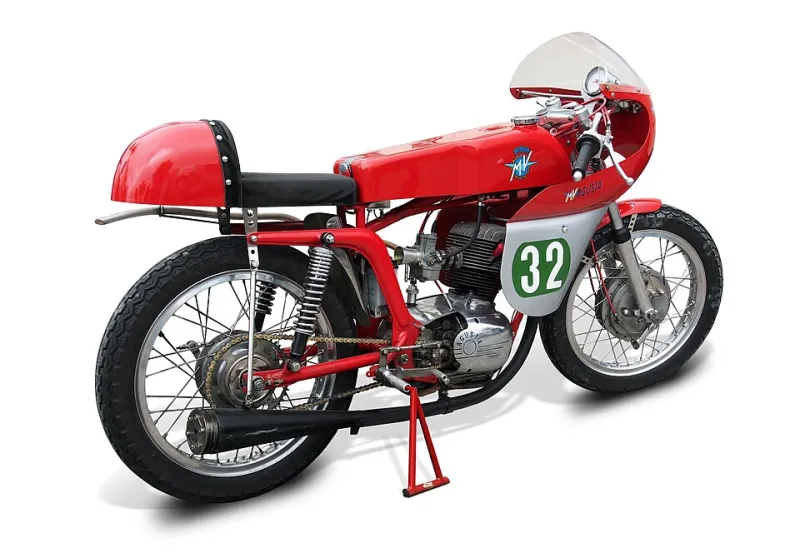
Photo: Foto: User:Alfvanbeem / Zusammenstellung, Retusche & Freisteller: Auge=mit, CC BY-SA 3.0, via Wikimedia Commons
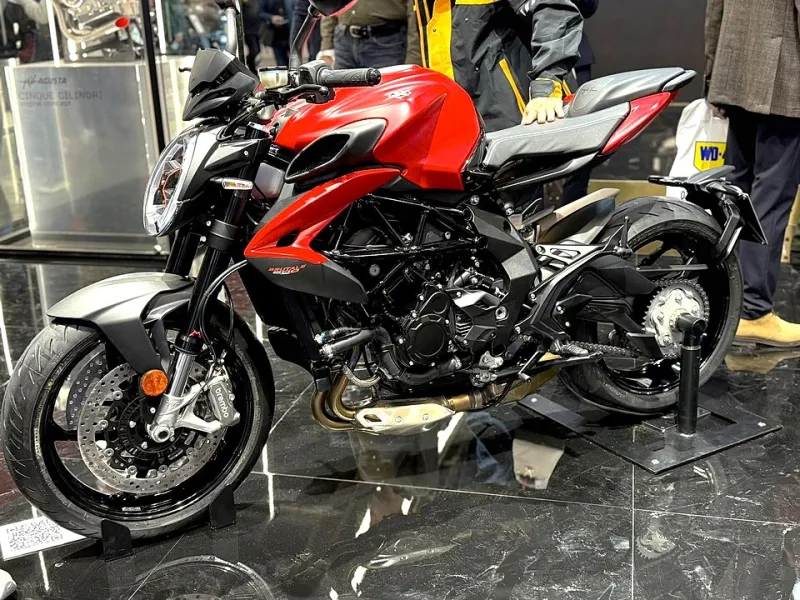
MV Agusta owners tend to have two conversations about insurance. The first is about price. The second is about value. The two are not the same, and in 2026 the gap matters more than ever. A Brutale, F3 or Superveloce is not just a motorcycle with a logbook. It is a design object, a weekend ritual and, for many owners, a long-term piece of the family. Insuring it like a generic commuter bike is the quickest way to feel underwhelmed when something goes wrong.
Agreed value is a contract, not a compliment
Standard motorcycle policies usually settle at market value at the time of loss. That sounds fair until you try to replace a low-volume Italian machine with the right spec, mileage and history. Agreed value works differently. You and the insurer fix a figure at the start of the policy, backed by evidence, and that figure becomes the reference point. It is not a vanity number. It is a negotiated estimate of what your bike is actually worth in the UK market.
The catch is admin. Expect to supply a valuation, dated photographs and a clear modification list. Specialist brokers know MV Agusta models move in narrow price bands, so a well-documented bike with service history is easier to defend than a vague one. Be honest about aftermarket parts. A tracker, exhaust, seat or carbon panel may add value, but only if the insurer knows it is there. Undeclared mods are the enemy of a smooth claim.
Build an evidence file before you need it
Take photographs on a dry day: both sides, front, rear, cockpit, odometer, VIN plate, engine number and any expensive extras. Add close-ups of marks so nobody can accuse you of hiding damage. Keep receipts for tyres, servicing, tracker installation and OEM parts. Store the lot in a cloud folder and update it at renewal. If your bike is financed, check how the settlement works with the finance house. If it is a long-term keeper, ask about salvage retention and laid-up cover for winter. These are unglamorous questions, but they are the difference between a policy and a plan.
Security is the other half of the premium
Insurers are not sentimental. They look at where the bike lives, how it is locked and whether recovery is realistic. A garage helps, but only if it is a garage in practice: door locked, alarm set, ground anchor fitted, chain through the frame rather than a wheel. If the bike sits outside, a cover is not security. It is a hint. Use a Sold Secure-rated chain and anchor where possible, and keep the tracker subscription active. A dormant tracker is a paperweight.
Trackers are worth the friction. Choose an insurance-approved unit with a monitoring plan you will actually renew. Pair it with the OEM immobiliser and an alarm that does not wake the street. In theft hotspots such as London, Birmingham, Manchester and the commuter belt around them, layers matter more than one heroic lock. Thieves do not read postcodes, and a quiet cul-de-sac is not a security plan.
Smart parking beats hopeful parking
The riskiest part of ownership is often the journey, not the garage. Hotel car parks, ferry terminals, motorway services and city bike bays are where opportunists work. Book accommodation with secure or underground parking, ask where the bike will actually sit, and take a lock even for a coffee stop. If you must park on-street, choose light, cameras and foot traffic over a dark side street. Cover the bike if you can, but do not rely on concealment alone. A disc lock is a delay, not a forcefield.
At home, think like a loss adjuster. Can the garage door be forced? Are the hinges exposed? Is the anchor bolted into something structural? Would a neighbour hear an angle grinder at 3am? These are not pleasant thoughts, but they are cheaper than a claim.
Treat it as art, insure it as transport
The contrarian point is simple: an MV Agusta deserves better than either blind sentiment or cheap cover. Insure the object, document the object, and secure the object as if it is both a sculpture and a daily ride. Agreed value protects the number. Evidence protects the claim. Security protects the bike. In 2026, that trio is the real premium package.